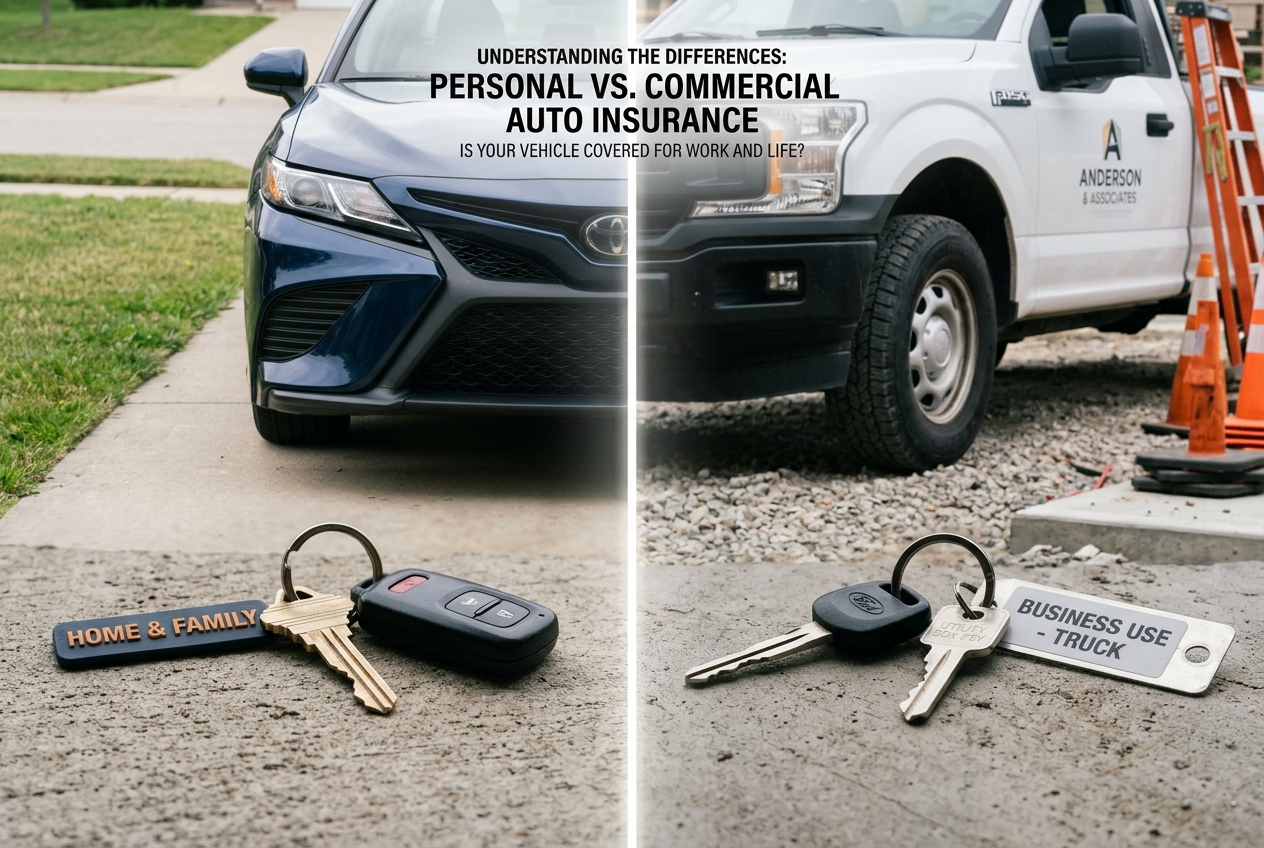
Is your pickup a personal vehicle or a business vehicle if you use it for both?
It’s one of the most common questions small business owners in Palmetto ask. The answer matters more than most people think. If the way you use a vehicle doesn’t match the policy you bought, a claim can get messy fast.
Here’s how the two types of coverage compare, and how to tell which one fits you.
Scope of coverage
Personal auto insurance is built for everyday life. Commuting, school runs, grocery trips, and weekend drives to the beach. It usually protects you, the people in your household, and others you let drive your car.
Commercial auto insurance is built for work. It protects the business that owns or uses the vehicle. It can cover several vehicles and many drivers on one policy. It often offers higher limits, which are the most a policy will pay for a covered claim.
The line between them isn’t always about the vehicle itself. A small sedan can need commercial coverage. A big pickup may stay on a personal policy if it’s truly used for personal driving.
According to the Insurance Information Institute, personal policies may cover some business use. They usually won’t cover a vehicle that’s used mainly for work or owned by a business. A personal policy also typically defends and pays only you, not your company. That’s a real gap if a lawsuit names your business.
Analyzing risk factors
Insurance companies look at risk, which is the chance of a claim and how big it might be. Work driving changes that picture.
Start with ownership. If the vehicle is titled to your business, it generally belongs on a commercial policy. Then look at what you carry. Tools, ladders, equipment, and trailers add weight and risk. So does carrying people or goods for pay.
Mileage and routes matter too. A plumber who drives between Ellenton job sites all day spends more time on the road than a typical commuter. More time on the road means more chances for a crash.
Weight is another big factor. Florida law sets higher liability minimums for commercial motor vehicles that weigh 26,000 pounds or more. Federal rules can apply as well. The agency that oversees trucks and buses says some carriers need a USDOT number when vehicles weigh 10,001 pounds or more and cross state lines. Florida also requires some in-state carriers to get one.
Finally, think about who drives. Employees, family members helping out, and new hires all change the risk.
Optimizing coverage
Getting the right fit starts with honesty. Tell your insurance company how you really use each vehicle. A misstated use can lead to a denied claim or a canceled policy.
If your work driving is light, ask whether your personal policy allows some business use. Some insurance companies allow it, often for an extra charge. Others won’t. Check your policy or ask us to look.
If you own several work vehicles or have employees behind the wheel, a commercial policy is usually the cleaner choice. Many commercial policies can add hired and non-owned auto coverage. It helps protect your business when staff drive their own or rented cars for work.
Don’t forget the umbrella question. A personal umbrella policy adds extra liability protection on top of your home and auto policies. But the Triple-I notes that personal umbrellas generally exclude business auto claims. Your commercial limits need to stand on their own.
Last, compare. Each insurance company draws these lines a little differently. That’s one reason working with an independent agency helps.
Frequently Asked Questions
What distinguishes personal from commercial auto insurance?
The main difference is who the policy protects. Personal auto covers you and your household for everyday driving. Commercial auto covers a business and the people who drive for it. Commercial policies often have higher limits and can list many vehicles and drivers. They’re also built for risks like hauling equipment, carrying goods, or driving to job sites all day.
How do I determine which type of insurance my vehicle needs?
Ask a few questions. Who owns the vehicle? How often is it used for work? Does it carry tools, goods, or paying passengers? Do employees drive it? How much does it weigh? If the business owns it or it’s used mostly for work, you likely need commercial coverage. When you’re unsure, an independent agent can review your situation.
Are there specific scenarios where commercial coverage is mandatory?
Yes, in some cases. Florida requires higher liability limits for commercial trucks at 26,000 pounds and up. Federal rules set minimums for many interstate carriers. Rideshare driving has its own rules, and Florida’s rideshare law lets personal insurers exclude coverage while you’re logged into an app. Clients and lenders may also require coverage by contract.
Sort out your vehicle coverage with a local team
The difference between personal and commercial auto isn’t always obvious. It often comes down to how you use the vehicle on an ordinary Tuesday.
That’s where a local agent helps. Anderson & Associates Insurance has been serving families and business owners since 1985 from our office on 8th Avenue West in Palmetto. We’re an independent agency, so we compare coverage from multiple insurance companies. We work for you, not for one insurer.
We’ll ask the right questions about your vehicles, your drivers, and your work. Then we’ll explain your options in plain language, so you know what you’re buying before you buy it. If you mostly drive for personal reasons, we can look at your personal auto insurance. If your vehicles keep your business running, we’ll walk through commercial auto coverage.
Either way, you won’t get pushed into something you don’t need.
Have questions about your own setup? Reach out to Anderson & Associates and schedule a coverage review with our team. We’re happy to help you sort it out.